Financial Planning Review in Singapore: 5 Essential Areas for a Better Financial Future
Table Of Contents
Introduction
Does the phrase “financial planning review” make you wonder whether you are about to be sold another insurance policy or investment?
You are not alone. You may genuinely want to know whether your finances are on track, but at the same time, you may not know what a proper financial review should cover, or what questions you should be asking. A good financial review should not start with “What else should I buy?” It should start with “Has anything in my life changed, and is my financial plan still right for me?”
And that means your review will look different depending on where you are in life. The five areas below are not five things everyone needs to review every year. In fact, only one or two may be particularly relevant to you right now. Think of them as a guide: start with what matters to your life today, while keeping an eye on what you may need to prepare for tomorrow.
What Should a Financial Planning Review Actually Do?
A useful financial planning review should help you take stock of where you are today and whether your existing plans still support where you want to go. Perhaps you have changed jobs, received a pay increase, bought a home, had a child, accumulated more investments or simply reached a different stage of life. Any of these could change your financial priorities.
The point is not to find something wrong every year. Sometimes, after reviewing everything, the conclusion may simply be: “I’m doing fine. Nothing needs to change right now.” That is a perfectly good outcome, too.
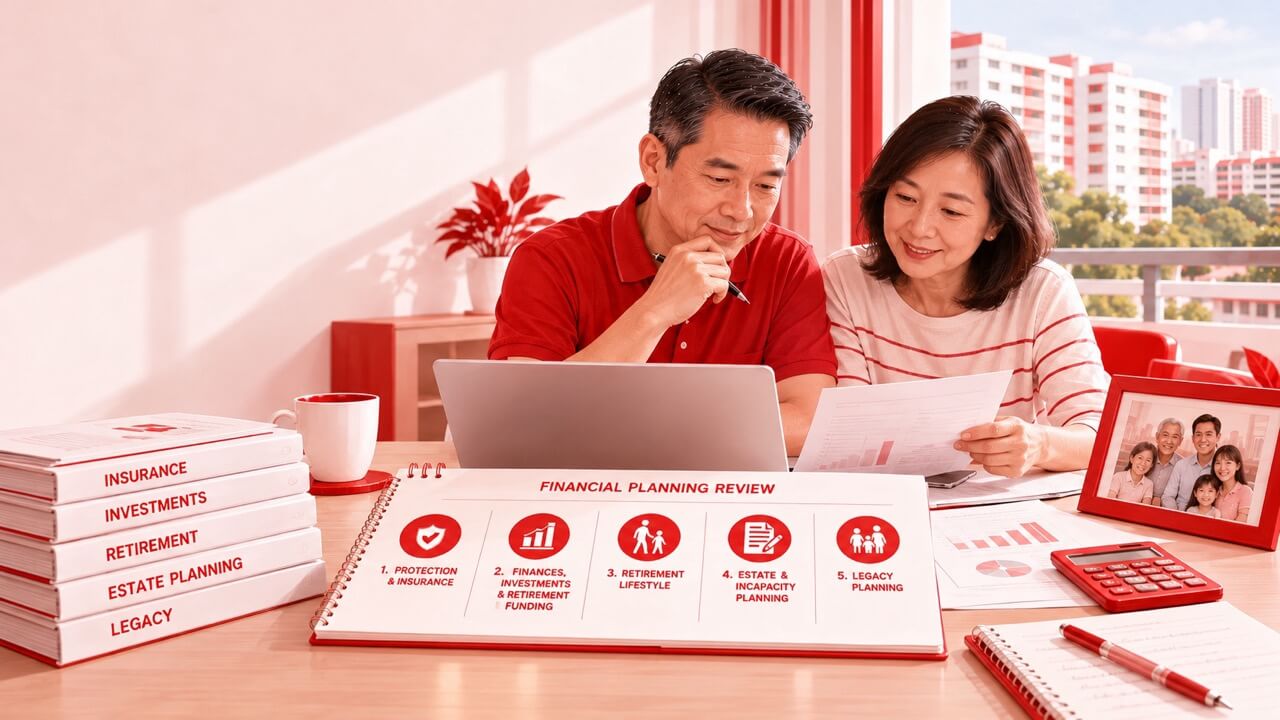
1) Protection & Insurance: Is Your Coverage Still Right for You?
Start by understanding what you already have. Do you know what your insurance policies actually cover, how much protection you have and whether the important policies are still active? It is surprisingly easy to remember buying a policy years ago, yet not remember exactly what it does today.
Then ask whether your protection still fits your current circumstances. Your income, debts, mortgage, dependants and family responsibilities may have changed considerably since you first bought your policies. A single person starting work and a parent supporting two children naturally have very different protection needs.
Most importantly, a protection review does not automatically mean buying more insurance. You might discover a genuine gap, but you might equally conclude that your existing coverage is sufficient. The purpose is to understand what you have and whether it still makes sense for your life today.
2) Finances, Investments & Retirement Funding: Are You Still on Track?
Take a high-level look at your overall financial position. Has your income changed? Are your expenses manageable? How are your savings and debts progressing? Then look at your investments, not simply at whether they went up or down last year, but whether they still suit your goals, time horizon and willingness to take risk.
This is also where you can review the financial side of retirement. Roughly how much income would you like when you eventually stop working? What could come from CPF LIFE, your investments, property or other sources? Based on what you are building today, are you broadly heading towards that number, or is there a potential shortfall worth addressing earlier?
You do not need to predict your future spending down to the last cup of kopi. The purpose is to get your direction roughly right. The earlier you identify a potential gap, the more time you usually have to make gradual adjustments rather than drastic ones later.
3) Retirement Lifestyle: What Are You Actually Retiring To?
Once you have asked “Can I afford to retire?”, there is another question that deserves just as much attention: “What am I actually retiring to?” Imagine your first Monday after retirement. There is no office to go to and no work schedule determining your day. What would you genuinely like your week to look like?
Perhaps it involves travelling, exercising, volunteering, spending time with your grandchildren, playing golf, learning something new, or simply having a regular group of friends to makan with. Whatever your answer, many of these things are easier to build before retirement. If you hope to have hiking friends at 65, perhaps start hiking with people at 55 rather than waiting until your retirement party.
Retirement planning should not be entirely about accumulating enough money. Financial readiness enables you to retire, and lifestyle readiness helps give retirement purpose.
4) Estate & Incapacity Planning: Will Your Wishes Be Known?
Some financial decisions become most important when you are no longer able to make those decisions yourself. Do you have a valid will, and does it still reflect what you want? Have you considered a Lasting Power of Attorney in case you lose mental capacity? Depending on your wishes, you may also want to understand Advance Medical Directives and Advance Care Planning.
There is also a very practical side to this. Does someone you trust know where your important financial and legal documents are kept? Does your family know whom to contact or what arrangements you would prefer if something happened to you? These conversations are easy to postpone precisely because nobody particularly enjoys having them.
But putting your wishes in order is not about expecting something bad to happen. It is about reducing confusion for the people you care about if they ever have to make difficult decisions on your behalf.
5) Legacy Planning: What Do You Want Your Wealth to Achieve?
Estate planning largely asks who should receive your assets. Legacy planning takes the conversation further: what do you want that wealth to do for the people who receive it?
Perhaps you want to help your children with their education or their first home. Perhaps you want to provide long-term financial security, support your grandchildren, or give your children the opportunity to start a business. You may also want to think about timing. Should everything be received immediately, or would a gradual distribution or structure be more appropriate? For some families, financial instruments or trusts may also be worth considering in that conversation.
The objective is not to control the next generation from beyond the grave. It is simply to ask whether the wealth you spent decades building will reach the right people in a way that reflects why you built it in the first place.
What Should You Do After Your Financial Review?
You do not need to walk away from your annual review with five pages of things to fix. Go back to the five areas above and identify the one or two that are most relevant to your current stage of life. Perhaps your protection needs attention this year. Perhaps you are approaching retirement and need to look more closely at retirement income. Or perhaps everything is broadly in order.
You can also use our Annual Financial Planning Review Checklist (PDF download) to work through these questions yourself. This is a free download, and no personal details are required. If the checklist highlights something you are unsure about, or you simply want a second pair of eyes, you can speak with one of our Premium Partner Advisers for a financial planning review.
There is no need to begin with a product. Begin with your life, your priorities and the questions that matter to you.
Frequently Asked Questions
A financial planning review is a check-up of your current financial arrangements to see whether they still align with your needs, goals, and stage of life. It can cover areas such as protection, investments, retirement, estate planning and legacy. However, not every area will be relevant to everyone at the same time.
An annual or biennial review is a useful starting point, but you should also consider reviewing your plan after a significant life change. This could include getting married, having a child, buying a home, changing jobs, approaching retirement or taking on new financial responsibilities.
A comprehensive review can look at five broad areas: protection and insurance, finances and investments, retirement funding, retirement lifestyle, and estate and legacy planning. However, you may only need to focus on one or two areas that are particularly relevant to you right now.
No. Your priorities will change as you move through different stages of life. A young family may focus more on protection and building wealth, while someone approaching retirement may spend more time reviewing retirement income, estate planning and legacy matters.
It helps to have a general picture of your income, expenses, savings, debts, investments and existing insurance policies. More importantly, think about what has changed in your life since your last review and whether you have any new financial goals or concerns.
No. A proper financial planning review should first determine whether your existing arrangements are still suitable. If everything remains appropriate, “no change needed” can be a perfectly good outcome of the review.
Look beyond whether your investments made or lost money recently. Consider whether they still match your financial goals, investment timeframe and willingness and ability to take risk. An investment that was suitable for you several years ago may not necessarily suit your circumstances today.
Retirement planning does not have to wait until you are close to retirement. Starting earlier gives you more time to understand what retirement might cost, what income you may have from sources such as CPF LIFE and investments, and whether there is a potential gap to address.
You can consider whether your will still reflects your wishes, whether a Lasting Power of Attorney is appropriate, and whether your important documents and instructions are accessible to someone you trust. You may also want to consider your healthcare wishes and whether tools such as Advance Care Planning or an Advance Medical Directive are relevant to you.
Estate planning generally focuses on how your assets and affairs should be handled when you pass away. Legacy planning goes further by asking what you want your wealth to achieve for the people or causes you care about. For example, education, housing, long-term security or support for future generations.
Yes. You can start by reviewing your finances with a structured checklist and identifying the areas that need attention. If you uncover something you do not understand, need help evaluating your options, or simply want a second opinion, you can then consider speaking with a financial adviser.
Related Articles
Useful Resources
Take the Next Step
Choose how you want to move forward